In the coming years, the financial management of Estonian companies will be shaped by the rapid development of technology, growing regulatory requirements and the need to make decisions in an increasingly uncertain economic environment. According to Mart Nõmper, partner and auditor at Grant Thornton Baltic, technological development will not reduce the importance of financial management or auditing. Instead, it will make data quality, well-organised processes and the ability to critically assess technology-driven decisions increasingly important.
“The biggest change is not one new tax or reporting requirement, but the fact that financial accounting is becoming increasingly automated and real-time. E-invoicing is a good example. In Estonia, a change that took effect in July 2025 allows a company registered in the Business Register as an e-invoice recipient to require the seller to issue a compliant e-invoice. The European Union is going even further: under the ViDA reform, digital reporting requirements based on e-invoicing will apply to cross-border B2B transactions from 2030,” says Nõmper.
For companies, this is a very practical change. Today, if an accountant manually corrects a wrongly entered customer code, VAT treatment or transaction date at the end of the month, incorrect information may in the future move automatically through the system. Automation does not make poor input better; it can actually make its impact faster and more widespread.
“To increase efficiency, companies should already review how much of their financial processes depends on Excel, manual data entry and the knowledge of individual employees,” Nõmper emphasises. “These are the areas where the greatest need for change will emerge in the coming years.”
Automation is changing the auditor’s work
Automation is also changing the role of the auditor. If technology can analyse an entire population of transactions, there is no longer much reason to spend most of an auditor’s time manually checking hundreds of individual invoices.
That does not mean, however, that the need for auditors will disappear, Nõmper says. “The focus of what the auditor checks is changing. For example, if a company uses an AI-based tool that predicts the likelihood of receivables being collected based on customers’ payment behaviour and helps assess the need for impairment, the model may work technically very well. But what happens if the historical data mainly comes from a period of economic growth? Or if a major customer, accounting for 50% of the receivable balance, runs into financial difficulties that the historical model cannot account for?”
In other words, AI provides an answer to the question it is asked, based on the data it is given. The auditor’s task is to ask whether the right question was asked, whether the data is reliable and whether the conclusion makes economic sense.
“AI reduces manual work in auditing, but not the importance of professional judgement. The more companies automate decisions, the more important it becomes to have independent assurance that the data, controls and assumptions behind those systems are reliable.”
Complexity increases tax risks
Tax risks usually do not arise from the most routine day-to-day transactions. Problems tend to emerge when transactions are complex, unusual or financially significant. Particular attention should be paid to cross-border activities.
For example, an Estonian company hires someone in Spain, a sales manager works in Finland for six months, or a board member manages part of the business from another country. For management, this may simply be a matter of organising people and work. From a tax perspective, however, questions may arise concerning the employee’s taxation, the employer’s registration obligations or even the creation of a permanent establishment in another country.
Another typical area, according to Nõmper, involves related-party transactions. An owner lends money to the company, one group company provides management services to another, or an Estonian company pays its foreign parent company for IT, management or licensing services. The existence of an invoice does not by itself mean that the tax treatment or transfer price is justified. The company must be able to demonstrate what service was actually received and why the price reflects market conditions.
The taxation of real estate transactions, corporate restructurings, mergers and acquisitions, and generational succession also remain areas where mistakes can be costly.
“I would recommend that managers carry out a practical exercise: take the ten most important financial and reporting processes in the company and ask who actually knows them. It is risky if the answer is that only Mari knows the entire process,” says Nõmper.
“If payroll exceptions exist only in one person’s head, only the person who created them understands the Excel formulas used for consolidation, or tax return corrections are made manually and the tax principles are not sufficiently described in the accounting policies, the problem is not just about efficiency. It is a risk to internal control and business continuity.”
He also points to access rights as an often-overlooked issue. Someone changes roles within the company but retains their previous permissions, a former employee’s user account remains active, or the same person can create a supplier, enter an invoice and approve a payment in the accounting system. These are not abstract IT risks but very concrete financial risks.
Instead of simply maintaining a list of regulations, every company should build a control environment where it is clear where data comes from, who changes it, who approves the transaction and how an error is detected. Periodically – for example, during the summer low season when workloads are lighter – companies should also conduct an access rights review to test the reliability of their control environment.
“Every company should build a control environment instead of simply maintaining a list of regulations: it should be clear where data comes from, who changes it, who approves the transaction and how an error is detected.”
Uncertainty comes at a cost for businesses
In addition to technology, companies’ competitiveness is affected by tax policy and European Union (EU) regulations.
According to Nõmper, the impact should not be assessed solely through tax rates, because for long-term investments, uncertainty can be equally important.
“Uncertainty also comes at a cost. Investments are often made over a five- or ten-year period. When a company builds a factory, hires one hundred people or enters a new market, the return on investment is calculated over a long period. If labour taxes, VAT, energy-related costs or reporting requirements change repeatedly during that time, investment risk increases even if each individual change does not seem dramatic.”
![Mart Nõmper]()
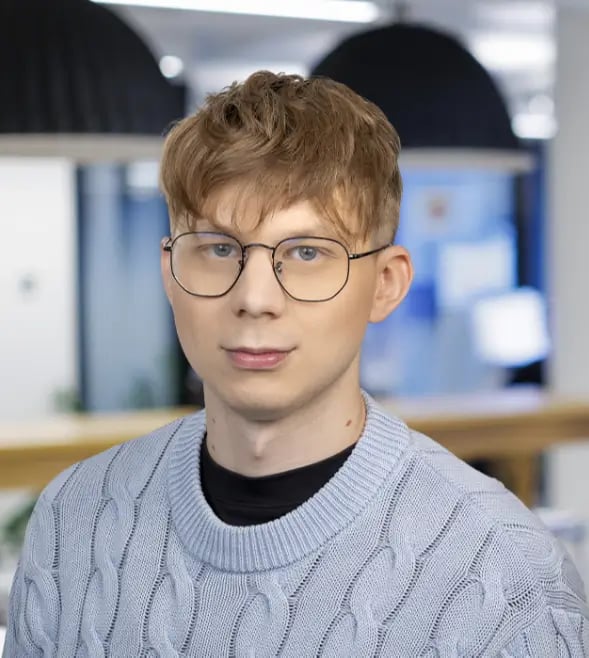
Mart Nõmper emphasises that finance managers must know how to use AI and challenge its output.
Photo: Manuel Mägi | Geenius
When it comes to regulation, businesses should pay particular attention to areas where requirements reach them indirectly. A small Estonian manufacturer may not itself be directly subject to a particular reporting obligation, but its large German or Swedish customer may start demanding more detailed information about the origin of raw materials, emissions, the supply chain or other indicators.
The same applies to tax reporting. The ViDA changes are moving EU cross-border B2B VAT reporting towards transaction-based digital reporting from 2030. A company whose ERP system currently contains incorrect customer data or whose invoicing process relies on manual corrections will not solve the underlying problem simply by adding another reporting form.
Finance managers need to be able to challenge AI
Technological development is also raising expectations of finance managers themselves. The finance manager of the future does not need to be a programmer, but they do need to understand how data moves through systems and through which controls it reaches management decisions.
Nõmper points out that finance managers must also know how to use AI and challenge its output.
“If AI prepares a budget, analyses a contract or forecasts cash flow, the finance manager cannot respond by saying, ‘that’s what the system calculated’. The responsibility for the decision remains with the human. Finance manager, you need more scepticism, common sense and critical thinking!”
The ability to connect a financial figure with the business decision behind it is what distinguishes a strong finance manager from a good accountant. If gross margin has fallen by three percentage points, simply reporting the decline is not enough. Was the reason pricing, the product portfolio, exchange rates, material costs or the fact that the sales team offered excessive discounts to increase volume? A good finance manager knows the answer.
There is particularly significant potential in small and medium-sized companies, where many support processes are still surprisingly manual. Customer communication may be fully digitalised, while inside the company the same information is still transferred manually from one system to another.
“I see huge potential for AI and automation here. For example, the system itself can match a purchase invoice with the order and the receipt of goods, while the employee deals only with exceptions. AI can extract payment terms, indexation clauses and other financially relevant conditions from contracts. It can automatically prepare the first analysis of a management report, allowing the finance team to spend its time understanding why a variance occurred and what to do about it,” says Nõmper.
At the same time, he warns that there is a major risk of automating a poor process.
“If the underlying data is poor, responsibilities are unclear and controls are weak, AI will simply execute the same process faster. That is why the greatest untapped potential lies in the combination of organised processes, high-quality data and only then technology.”
Future resilience starts with questioning assumptions
Long-term financial strength requires more than good technology or an accurate budget.
“I would recommend that managers identify the five assumptions that need to hold true for the company’s current business model to work, and consider what happens if one of them no longer applies. For example: our largest customer remains a customer, the bank refinances the loan, key employees stay with the company, input costs do not rise above a certain level, and our product remains technologically competitive. But what do we do if one of these assumptions no longer holds?”
According to Nõmper, this is a much more valuable exercise than preparing yet another five-year budget based on a single “likely” scenario.
“A strong company is not one whose forecast is always accurate. A strong company is one that has enough capital, information and management capacity to act even when reality diverges significantly from the forecast.”