Watch the Nordic-Baltic tax outlook 2025–2026 webinar
Tax experts from seven countries discuss key Nordic-Baltic tax developments, enforcement trends and legislative changes. Watch the webinar recording.
11 Aug 2026 2 min read
Grant Thornton Baltic has been named a finalist in the ITR Europe Tax Awards 2026, an awards competition organised by the international tax publication International Tax Review (ITR).
ITR recognised Grant Thornton Baltic for its professional work in the field of transfer pricing. The nomination highlights the ability of Grant Thornton Baltic’s tax advisory team to provide high-quality services to our internationally active clients across the Baltics.
“For more than 20 years, we have worked as one team, combining the knowledge and experience of experts from Estonia, Latvia and Lithuania. We are pleased that our team’s efforts and smooth cooperation have also been noticed by the international tax community,” said Kristjan Järve, Partner at Grant Thornton Baltic and Head of Tax Advisory.
The ITR Europe Tax Awards are among the best-known awards in the European tax sector and have been presented since 2005. In 2026, tax and transfer pricing teams in 33 jurisdictions were assessed, with attention also paid to innovation in tax technology, compliance, and the promotion of diversity, equity and inclusion.
Founded in 1992, Grant Thornton Baltic is one of the leading providers of audit, accounting, tax, legal, financial and business advisory services in the Baltics. Operating in Estonia, Latvia and Lithuania, the company has a total of six offices, more than 350 employees and over 2,600 clients. Grant Thornton Baltic is part of the global Grant Thornton network of advisory firms, which operates in more than 150 countries.
To stay informed about economic developments, legal updates, and key trends in our services, subscribe to our newsletter.
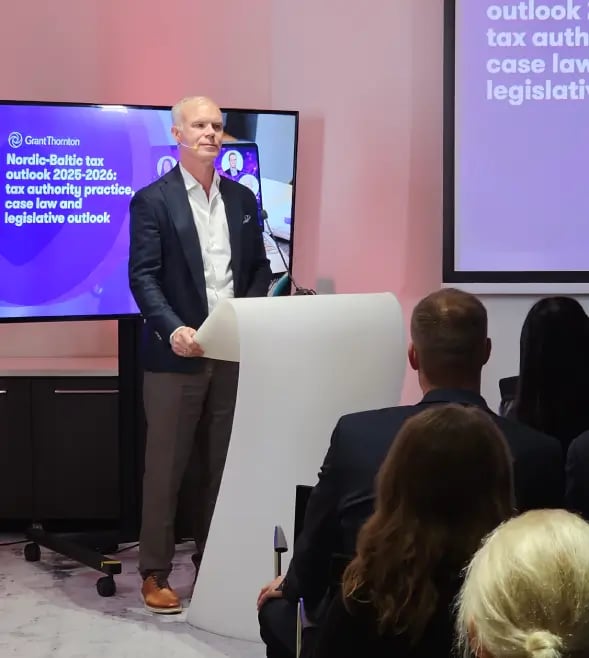
Tax experts from seven countries discuss key Nordic-Baltic tax developments, enforcement trends and legislative changes. Watch the webinar recording.
The taxation of salaries paid to local employees of foreign embassies often raises questions in practice. In particular, it may be unclear why income tax is not withheld from the salary, why the salary is declared in Annex 1 to the TSD tax return using payment type 11, and why the employee must pay the income tax themselves.
From a taxation and accounting perspective, gift cards are not merely payment instruments. Their treatment depends both on the type of gift card and on whether the card is sold or given away free of charge. Therefore, now is a good time to revisit when and how gift cards should be taxed and how they should be properly recognised in accounting.
